AI Disinflation Could Lower Mortgage Rates Through Job Losses, Not Economic Growth
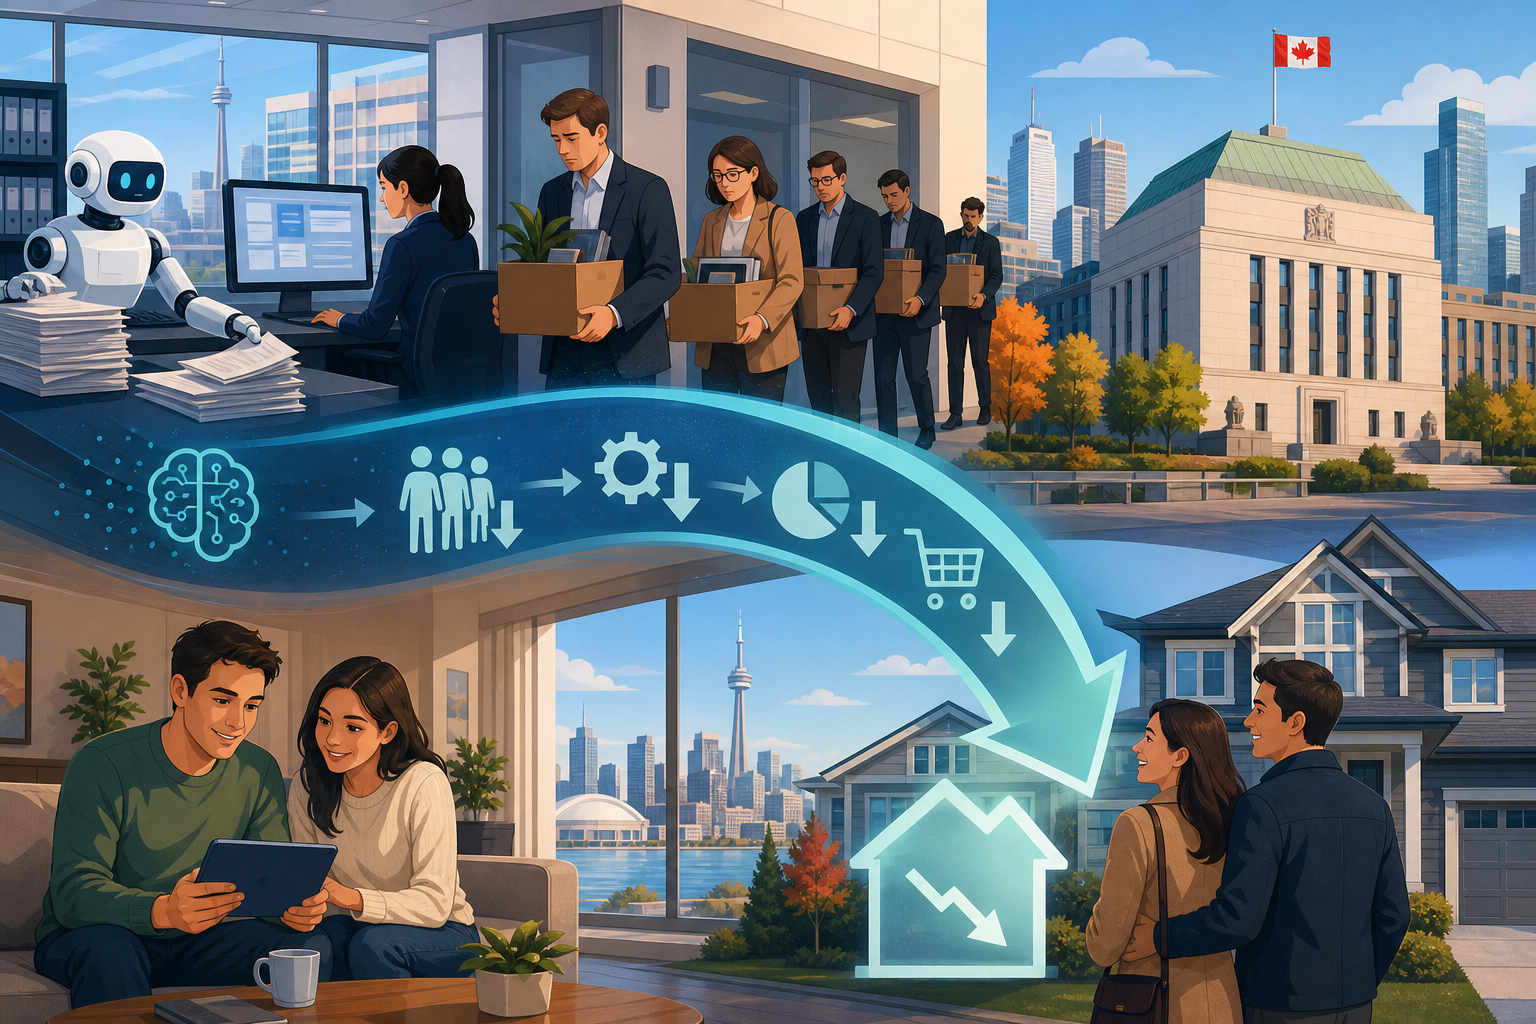
Canada's 5-year fixed insured mortgage rates were in the low-4% range in June 2026, down from higher levels six months earlier. The Bank of Canada cut rates twice in that window. Most analysts credited cooling inflation. Few mentioned the thousands of white-collar jobs that vanished over the same period, many of them replaced by generative AI workflows in finance, legal, and administrative sectors.
Job loss is the mechanism behind the rate drop, not incidental to it.
The Mechanics of AI Disinflation
AI drives productivity higher by automating tasks that used to require headcount. A mid-sized law firm that once needed twelve paralegals for document review now needs four, plus a subscription to a generative AI service at a fraction of the prior salary cost. Output stays flat or rises. Wages fall in aggregate. The result is lower production costs across services, which account for approximately 75% of Canadian GDP. When service costs drop, the Consumer Price Index follows.
The Bank of Canada watches slack. When unemployment ticks up and inflation undershoots the 2% target, the overnight rate comes down to stimulate demand. That transmission takes 18 to 24 months, but bond markets move faster. The 5-year Government of Canada bond yield drops the moment investors expect sustained low inflation. Fixed mortgage rates, which trade at a spread of 100 to 250 basis points over that bond yield, drop in lockstep.
The difference between this cycle and prior rate cuts: there is no recession forcing the central bank's hand. The economy is not contracting. AI is simply making it cheaper to produce the same output with fewer people.
Who Benefits, Who Pays
A household renewing a $450,000 mortgage in late 2026 at 4.5% instead of 5.5% saves approximately $270 per month, or roughly $16,200 over five years. That savings is real. It comes from the labour market absorbing displaced workers who no longer bid up wages. The mortgage holder benefits from the lower rate. The displaced worker loses income.
Canadians remain among the most indebted in the G7. Any downward movement in borrowing costs provides immediate household relief, especially for those renewing mortgages taken at pandemic-era prices. But if that relief is funded by job losses in the borrower's own sector, the trade is fragile. A lower rate helps only if you keep your income.
The sector vulnerability is new. Previous automation waves hit manufacturing and logistics, blue-collar work that was spatially concentrated. AI hits knowledge work: finance, legal services, HR, marketing, administrative functions. These are distributed across the entire economy and were historically considered safe. The productivity gain is faster because the tasks AI replaces are already digital.
The Boundary Case
The disinflationary effect holds only if displaced workers do not find equivalent wages elsewhere. If AI creates as many jobs as it destroys, wage pressure stays neutral and inflation does not break. History suggests a lag: new job categories emerge, but not immediately. During that lag, the labour market weakens and rates fall.
The flip case is energy and hardware costs. Running data centres at scale is energy-intensive. If electricity demand from data centres drives power prices higher, that acts as an inflationary shock on the supply side, potentially offsetting the deflationary wage effect. Ontario's IESO projects 2.2% compound annual growth in peak electricity demand through 2050, much of it driven by industrial computing loads. Whether that cost is passed through to consumers or absorbed by tech companies determines which force wins.
For mortgage rates, the near-term path is clear. Lower job growth, lower inflation, lower rates. The housing market may interpret falling rates as affordability returning. The affordability here rests on job losses. Your monthly payment prices in cost-cutting, not growth.



Canada's 5-year fixed insured mortgage rates were in the low-4% range in June 2026, down from higher levels six months earlier. The Bank of Canada cut rates twice in that window. Most analysts credited cooling inflation. Few mentioned the thousands of white-collar jobs that vanished over the same period, many of them replaced by generative AI workflows in finance, legal, and administrative sectors.
Job loss is the mechanism behind the rate drop, not incidental to it.
The Mechanics of AI Disinflation
AI drives productivity higher by automating tasks that used to require headcount. A mid-sized law firm that once needed twelve paralegals for document review now needs four, plus a subscription to a generative AI service at a fraction of the prior salary cost. Output stays flat or rises. Wages fall in aggregate. The result is lower production costs across services, which account for approximately 75% of Canadian GDP. When service costs drop, the Consumer Price Index follows.
The Bank of Canada watches slack. When unemployment ticks up and inflation undershoots the 2% target, the overnight rate comes down to stimulate demand. That transmission takes 18 to 24 months, but bond markets move faster. The 5-year Government of Canada bond yield drops the moment investors expect sustained low inflation. Fixed mortgage rates, which trade at a spread of 100 to 250 basis points over that bond yield, drop in lockstep.
The difference between this cycle and prior rate cuts: there is no recession forcing the central bank's hand. The economy is not contracting. AI is simply making it cheaper to produce the same output with fewer people.
Who Benefits, Who Pays
A household renewing a $450,000 mortgage in late 2026 at 4.5% instead of 5.5% saves approximately $270 per month, or roughly $16,200 over five years. That savings is real. It comes from the labour market absorbing displaced workers who no longer bid up wages. The mortgage holder benefits from the lower rate. The displaced worker loses income.
Canadians remain among the most indebted in the G7. Any downward movement in borrowing costs provides immediate household relief, especially for those renewing mortgages taken at pandemic-era prices. But if that relief is funded by job losses in the borrower's own sector, the trade is fragile. A lower rate helps only if you keep your income.
The sector vulnerability is new. Previous automation waves hit manufacturing and logistics, blue-collar work that was spatially concentrated. AI hits knowledge work: finance, legal services, HR, marketing, administrative functions. These are distributed across the entire economy and were historically considered safe. The productivity gain is faster because the tasks AI replaces are already digital.
The Boundary Case
The disinflationary effect holds only if displaced workers do not find equivalent wages elsewhere. If AI creates as many jobs as it destroys, wage pressure stays neutral and inflation does not break. History suggests a lag: new job categories emerge, but not immediately. During that lag, the labour market weakens and rates fall.
The flip case is energy and hardware costs. Running data centres at scale is energy-intensive. If electricity demand from data centres drives power prices higher, that acts as an inflationary shock on the supply side, potentially offsetting the deflationary wage effect. Ontario's IESO projects 2.2% compound annual growth in peak electricity demand through 2050, much of it driven by industrial computing loads. Whether that cost is passed through to consumers or absorbed by tech companies determines which force wins.
For mortgage rates, the near-term path is clear. Lower job growth, lower inflation, lower rates. The housing market may interpret falling rates as affordability returning. The affordability here rests on job losses. Your monthly payment prices in cost-cutting, not growth.
Sources
Read Next
How Dual Citizens Can Claim RESP Tax Benefits Without Form 3520 Reporting
Bond Markets Are Pricing In Recovery, Not the 1970s Replay Already Underway
Why Fortress Tells Private Credit Lenders to Stop Chasing AI Data Centre Deals
Canada's Tax Code Punishes Work and Rewards Wealth Hoarding: Four Reforms That Would Actually Fix It