Canada's 75,100 New Jobs Look Strong Until You Check Who's Actually Hiring
Statistics Canada reported the 75,100-job gain last month alongside an unemployment rate that dropped to its lowest point since August 2024. Markets had expected roughly half that number. The headline looks like vindication for anyone who argued the Canadian economy had bottomed out earlier this year.
But the number that matters isn't the 75,100. It's where those jobs came from.
The Public Sector Is Doing the Heavy Lifting
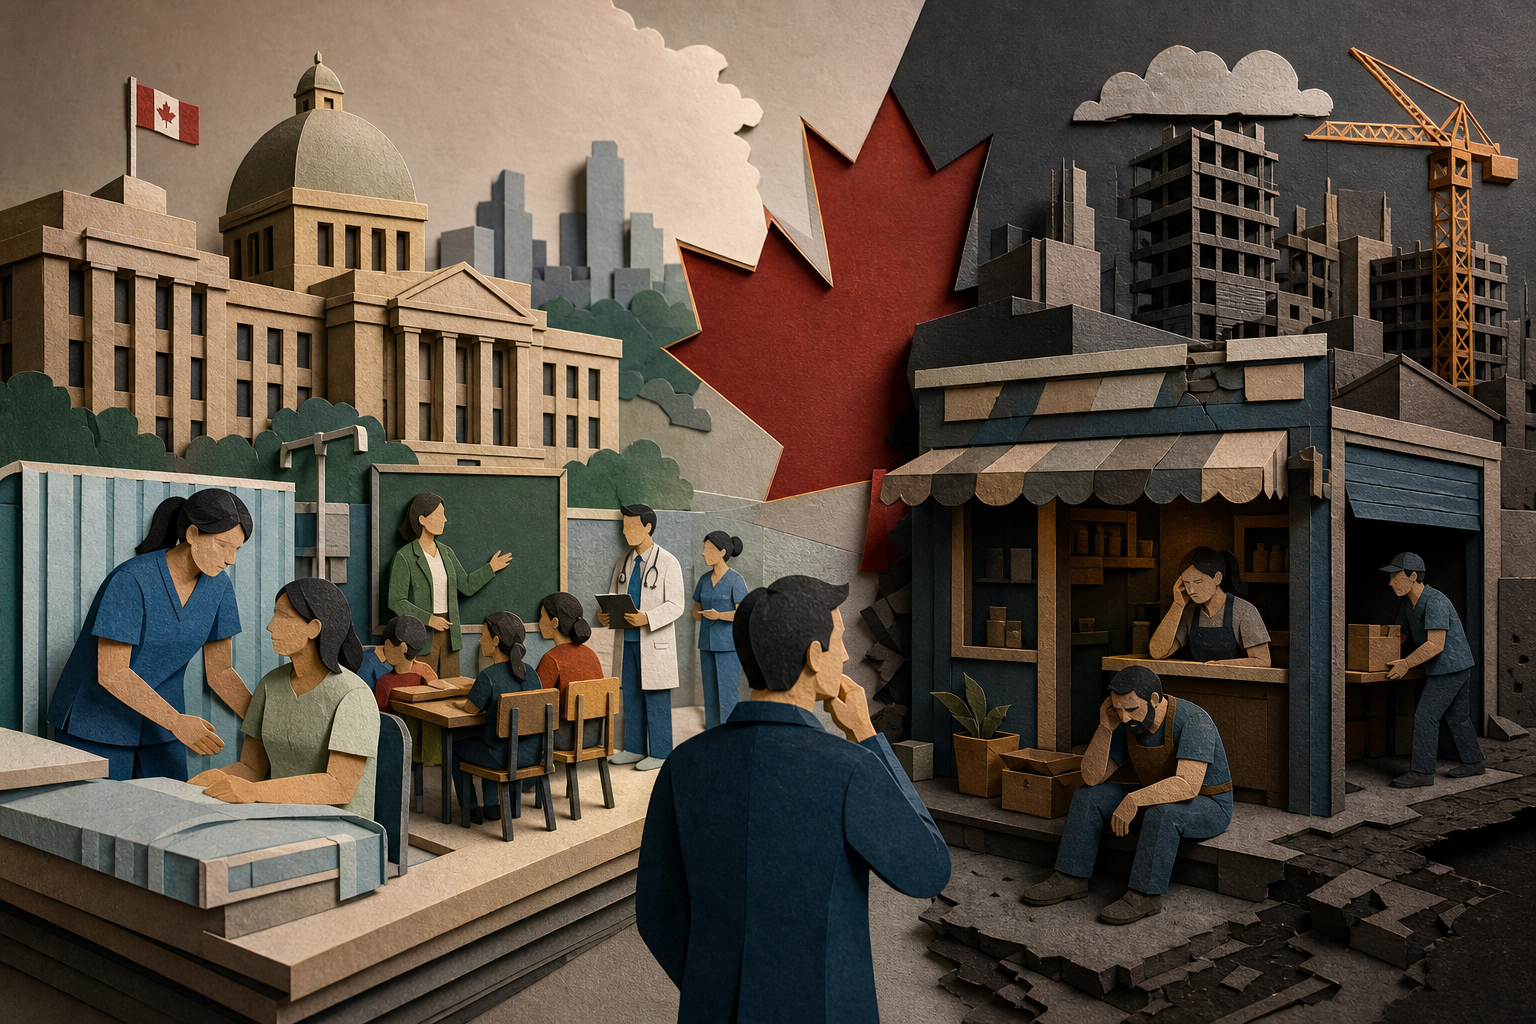
When you break down the August figures by employer type, a pattern emerges that complicates the recovery narrative. Public-sector employment, government administration, healthcare, education, accounted for the bulk of the gains. These aren't jobs created by rising business confidence or stronger consumer demand. They're jobs funded by tax revenue and deficit spending, often tied to policy commitments made months or years earlier.
A hospital in Hamilton hiring 40 nurses to clear surgical backlogs is a real job for those 40 people. But it tells you nothing about whether private employers in Hamilton think the next twelve months look strong enough to expand payroll. The public sector hires to meet service obligations. The private sector hires when it expects revenue growth to justify the cost. One is a leading indicator. The other isn't.
In previous recoveries, private-sector job creation typically led the rebound. Businesses expanded capacity, retail and hospitality ramped up, and construction firms staffed up ahead of anticipated demand. That sequence hasn't shown up yet in the 2026 data. Manufacturing added jobs, but modestly. Professional services were flat. Retail remains choppy, with gains in one month erased the next.
What the Unemployment Rate Is Hiding
The two-year low in unemployment sounds reassuring until you account for labor force participation. If fewer people are actively looking for work, the unemployment rate falls even when job creation is weak. August's participation rate held steady, which is better than a decline, but it's not rising either. That means the unemployment drop is legitimate in the narrow sense, more people have jobs relative to those seeking them, but it doesn't signal an economy pulling idle workers back in.
The composition of the 75,100 also matters. Full-time positions grew, which is a positive. But the share of workers in temporary or contract roles remains elevated compared to pre-pandemic norms. A full-time public-sector contract that ends in eighteen months when the funding envelope closes is not the same thing as a salaried private-sector hire with benefits and job security tied to the firm's long-term outlook.
The Mortgage Industry Should Stay Cautious
For lenders, these numbers create a false sense of stability. Employment strength reduces near-term default risk, which is real and welcome. But if that strength is concentrated in government payrolls rather than private business expansion, it doesn't predict sustained income growth or rising home-buying capacity in 2027 and beyond.
The Bank of Canada now faces a more complicated decision on rates. Strong headline employment data argues against further cuts, even if the underlying drivers, public spending rather than organic growth, suggest the economy still needs support. If rates stay elevated longer because the unemployment figure looks too good, you get the worst of both worlds: higher borrowing costs without the private-sector expansion that would justify them.
The 75,100 jobs are real. The people hired will spend the income. But when the engine of growth is the public sector rather than business investment and consumer confidence, the recovery has a ceiling built in. That ceiling is the fiscal capacity of governments that are already running deficits and facing demographic pressure on healthcare and pension spending.
August's numbers bought some time. They didn't solve the underlying question of whether Canadian businesses believe conditions are strong enough to expand on their own.



Statistics Canada reported the 75,100-job gain last month alongside an unemployment rate that dropped to its lowest point since August 2024. Markets had expected roughly half that number. The headline looks like vindication for anyone who argued the Canadian economy had bottomed out earlier this year.
But the number that matters isn't the 75,100. It's where those jobs came from.
The Public Sector Is Doing the Heavy Lifting
When you break down the August figures by employer type, a pattern emerges that complicates the recovery narrative. Public-sector employment, government administration, healthcare, education, accounted for the bulk of the gains. These aren't jobs created by rising business confidence or stronger consumer demand. They're jobs funded by tax revenue and deficit spending, often tied to policy commitments made months or years earlier.
A hospital in Hamilton hiring 40 nurses to clear surgical backlogs is a real job for those 40 people. But it tells you nothing about whether private employers in Hamilton think the next twelve months look strong enough to expand payroll. The public sector hires to meet service obligations. The private sector hires when it expects revenue growth to justify the cost. One is a leading indicator. The other isn't.
In previous recoveries, private-sector job creation typically led the rebound. Businesses expanded capacity, retail and hospitality ramped up, and construction firms staffed up ahead of anticipated demand. That sequence hasn't shown up yet in the 2026 data. Manufacturing added jobs, but modestly. Professional services were flat. Retail remains choppy, with gains in one month erased the next.
What the Unemployment Rate Is Hiding
The two-year low in unemployment sounds reassuring until you account for labor force participation. If fewer people are actively looking for work, the unemployment rate falls even when job creation is weak. August's participation rate held steady, which is better than a decline, but it's not rising either. That means the unemployment drop is legitimate in the narrow sense, more people have jobs relative to those seeking them, but it doesn't signal an economy pulling idle workers back in.
The composition of the 75,100 also matters. Full-time positions grew, which is a positive. But the share of workers in temporary or contract roles remains elevated compared to pre-pandemic norms. A full-time public-sector contract that ends in eighteen months when the funding envelope closes is not the same thing as a salaried private-sector hire with benefits and job security tied to the firm's long-term outlook.
The Mortgage Industry Should Stay Cautious
For lenders, these numbers create a false sense of stability. Employment strength reduces near-term default risk, which is real and welcome. But if that strength is concentrated in government payrolls rather than private business expansion, it doesn't predict sustained income growth or rising home-buying capacity in 2027 and beyond.
The Bank of Canada now faces a more complicated decision on rates. Strong headline employment data argues against further cuts, even if the underlying drivers, public spending rather than organic growth, suggest the economy still needs support. If rates stay elevated longer because the unemployment figure looks too good, you get the worst of both worlds: higher borrowing costs without the private-sector expansion that would justify them.
The 75,100 jobs are real. The people hired will spend the income. But when the engine of growth is the public sector rather than business investment and consumer confidence, the recovery has a ceiling built in. That ceiling is the fiscal capacity of governments that are already running deficits and facing demographic pressure on healthcare and pension spending.
August's numbers bought some time. They didn't solve the underlying question of whether Canadian businesses believe conditions are strong enough to expand on their own.
Read Next
How Dual Citizens Can Claim RESP Tax Benefits Without Form 3520 Reporting
Bond Markets Are Pricing In Recovery, Not the 1970s Replay Already Underway
Why Fortress Tells Private Credit Lenders to Stop Chasing AI Data Centre Deals
Canada's Tax Code Punishes Work and Rewards Wealth Hoarding: Four Reforms That Would Actually Fix It