H&R REIT's $3.4-Billion Fire Sale Drew Buyers but Not Believers
GO Residential REIT and a syndicate of institutional buyers just committed $3.4 billion to acquire a large slice of H&R's residential holdings, marking one of the largest portfolio transactions in Canadian REIT history. H&R's units fell 1.3% the same day.
That's the arithmetic of a fire sale that cleared the market but failed to move sentiment. H&R positioned the deal as strategic repositioning, shedding U.S. multi-family assets to concentrate on urban office and development pipelines in core Canadian and American cities. The Street heard something else: desperation dressed up as focus.
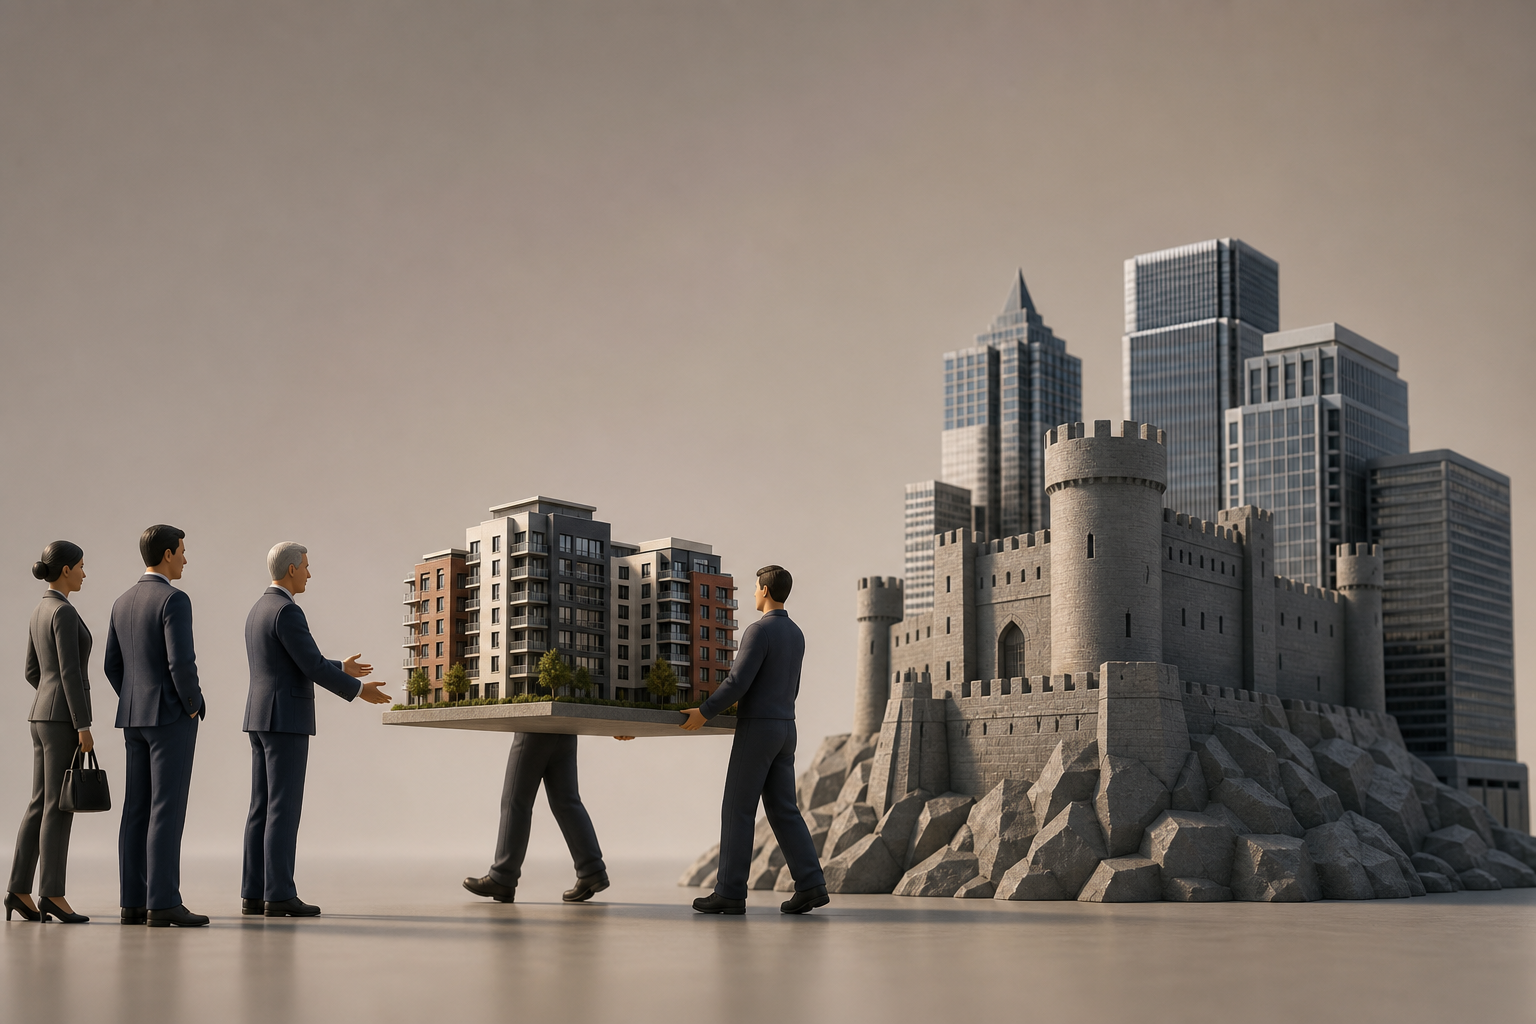
Selling the Crown to Save the Castle
The residential portfolio H&R is offloading was the defensible part of its book. Multi-family properties in secondary U.S. markets delivered predictable cash flow and occupied a segment where institutional buyers remain hungry. Office holdings, particularly the urban cores H&R claims as its future, remain under structural pressure from hybrid work adoption. Vacancy rates in Toronto's financial district hovered near 15% in early 2026, up from roughly 8% pre-pandemic.
So H&R is selling what buyers want to fix a balance sheet weighed down by what they don't. The proceeds, earmarked for debt reduction and funding new development, will shore up leverage ratios and theoretically narrow the NAV gap, the discount between trading price and underlying asset value. H&R has historically traded 20% to 30% below its stated net asset value, a reflection of investor skepticism that management can extract full value from a sprawling, mixed-use empire.
The problem is that selling assets to pay down debt only solves the solvency question. It doesn't solve the growth question. REITs trade on future cash flow, not just balance sheet strength. Stripping out residential income to fund office developments in a sector still searching for a post-pandemic clearing price is a bet that requires execution H&R has not yet demonstrated at scale.
The Trust Deficit
A $3.4-billion transaction should be a headline event, the kind of capital markets moment that resets the valuation narrative. Instead, units dropped. That's not noise. It's a verdict.
Institutional buyers clearly see value in the assets, GO Residential and its partners wouldn't deploy that much capital without conviction. But the market is pricing H&R on what's left, not what it sold. After the close, H&R will be a simplified, concentrated play on urban office and greenfield development. The first has structural headwinds. The second requires flawless execution in an environment where construction costs remain elevated and cap rates continue to widen.
Investors have heard "strategic repositioning" from H&R before. Activist shareholders pushed for asset sales and portfolio simplification as far back as 2019. The REIT has been unwinding complexity for years, yet the NAV gap persists. Markets reward clarity, but only when clarity produces per-unit growth. So far, H&R's simplification efforts have mostly produced a smaller company.
Price Discovery in a Soft Market
The one piece of signal this deal provides is a valuation benchmark. $3.4 billion for a large residential portfolio sets a cap rate floor that other Canadian and U.S. REITs will use to mark their own books. GO Residential's willingness to deploy that much capital suggests institutional appetite for multi-family remains intact, even as overall REIT valuations stay compressed.
But H&R unitholders aren't GO Residential. They're stuck holding the office bet.
The Bank of Canada's policy rate sits at 4.25% in mid-2026, down from the 5% peak but still well above the sub-2% environment that made leveraged real estate an easy trade. Higher-for-longer rates mean REITs need operational performance to justify valuations, not just low borrowing costs. H&R just sold the operationally stable part of its portfolio.
That's not a fire sale in the distressed sense. It's a fire sale in the opportunity-cost sense. The buyers got the good part. The believers stayed home.



GO Residential REIT and a syndicate of institutional buyers just committed $3.4 billion to acquire a large slice of H&R's residential holdings, marking one of the largest portfolio transactions in Canadian REIT history. H&R's units fell 1.3% the same day.
That's the arithmetic of a fire sale that cleared the market but failed to move sentiment. H&R positioned the deal as strategic repositioning, shedding U.S. multi-family assets to concentrate on urban office and development pipelines in core Canadian and American cities. The Street heard something else: desperation dressed up as focus.
Selling the Crown to Save the Castle
The residential portfolio H&R is offloading was the defensible part of its book. Multi-family properties in secondary U.S. markets delivered predictable cash flow and occupied a segment where institutional buyers remain hungry. Office holdings, particularly the urban cores H&R claims as its future, remain under structural pressure from hybrid work adoption. Vacancy rates in Toronto's financial district hovered near 15% in early 2026, up from roughly 8% pre-pandemic.
So H&R is selling what buyers want to fix a balance sheet weighed down by what they don't. The proceeds, earmarked for debt reduction and funding new development, will shore up leverage ratios and theoretically narrow the NAV gap, the discount between trading price and underlying asset value. H&R has historically traded 20% to 30% below its stated net asset value, a reflection of investor skepticism that management can extract full value from a sprawling, mixed-use empire.
The problem is that selling assets to pay down debt only solves the solvency question. It doesn't solve the growth question. REITs trade on future cash flow, not just balance sheet strength. Stripping out residential income to fund office developments in a sector still searching for a post-pandemic clearing price is a bet that requires execution H&R has not yet demonstrated at scale.
The Trust Deficit
A $3.4-billion transaction should be a headline event, the kind of capital markets moment that resets the valuation narrative. Instead, units dropped. That's not noise. It's a verdict.
Institutional buyers clearly see value in the assets, GO Residential and its partners wouldn't deploy that much capital without conviction. But the market is pricing H&R on what's left, not what it sold. After the close, H&R will be a simplified, concentrated play on urban office and greenfield development. The first has structural headwinds. The second requires flawless execution in an environment where construction costs remain elevated and cap rates continue to widen.
Investors have heard "strategic repositioning" from H&R before. Activist shareholders pushed for asset sales and portfolio simplification as far back as 2019. The REIT has been unwinding complexity for years, yet the NAV gap persists. Markets reward clarity, but only when clarity produces per-unit growth. So far, H&R's simplification efforts have mostly produced a smaller company.
Price Discovery in a Soft Market
The one piece of signal this deal provides is a valuation benchmark. $3.4 billion for a large residential portfolio sets a cap rate floor that other Canadian and U.S. REITs will use to mark their own books. GO Residential's willingness to deploy that much capital suggests institutional appetite for multi-family remains intact, even as overall REIT valuations stay compressed.
But H&R unitholders aren't GO Residential. They're stuck holding the office bet.
The Bank of Canada's policy rate sits at 4.25% in mid-2026, down from the 5% peak but still well above the sub-2% environment that made leveraged real estate an easy trade. Higher-for-longer rates mean REITs need operational performance to justify valuations, not just low borrowing costs. H&R just sold the operationally stable part of its portfolio.
That's not a fire sale in the distressed sense. It's a fire sale in the opportunity-cost sense. The buyers got the good part. The believers stayed home.
Read Next
How Dual Citizens Can Claim RESP Tax Benefits Without Form 3520 Reporting
Bond Markets Are Pricing In Recovery, Not the 1970s Replay Already Underway
Why Fortress Tells Private Credit Lenders to Stop Chasing AI Data Centre Deals
Canada's Tax Code Punishes Work and Rewards Wealth Hoarding: Four Reforms That Would Actually Fix It