The Mortgage Stress Test Qualifies You for the Loan, Not the Rate Shock
A borrower in Markham closed on a $680,000 mortgage in March 2021 at 1.49% variable. She qualified under the stress test at 5.25%. Two years later, her rate sat at 6.45%, higher than the rate she was tested against, and her monthly payment had climbed $1,340. She passed the bank's test. The bank got paid. She sold the house.
The Office of the Superintendent of Financial Institutions requires lenders to qualify borrowers at the higher of the contract rate plus 200 basis points or a floor rate of 5.25%. This is OSFI Guideline B-20, and it has been in place since 2018. The purpose is systemic: to prevent a wave of defaults that would threaten the stability of the financial system. It does that job. What it does not do is protect the individual borrower from payment shock at renewal or from lifestyle erosion during a rate cycle.
What the Test Actually Measures
The stress test calculates two ratios. Gross Debt Service accounts for shelter costs: mortgage payment, property tax, heating, and half of condo fees. Total Debt Service adds all other debt: car loans, credit cards, lines of credit. The maximums are typically 39% and 44% of gross household income. If you clear those thresholds at the stressed rate, you qualify.
Notice what is missing. Childcare, which for two kids in Toronto runs $2,800 a month. Groceries, up 22% since 2021 according to Statistics Canada. Private school. Car insurance, which in Ontario has climbed 15% in two years. The bank's formula treats discretionary income as infinite once debt service is covered, ignoring the groceries you buy, the childcare your kids need, and the car insurance you cannot skip.
The test also ignores timing. It measures affordability at application, when income is declared and debt is frozen in time. Three years later, you may have added a car lease, a second child, or a home equity line of credit to cover a kitchen reno. The original stress test did not anticipate those.
The Variable Rate Problem
Variable-rate holders with static payments face a structural trap the stress test does not address. As rates rise, more of each payment goes to interest. Eventually you hit the trigger point: your monthly payment only covers interest, and principal begins to grow. CIBC estimated in early 2024 that 32% of its variable-rate mortgage holders had reached trigger.
The stress test confirmed you could afford a higher rate. It did not confirm you could afford a mortgage balance that increases month over month while your equity shrinks.
The Renewal Wall
Roughly $340 billion in mortgages are renewing between 2025 and 2027, most of them originated when five-year fixed rates sat below 2.5%. A borrower who locked in at 1.79% in 2020 qualified at 4.79%. That same borrower renewing in 2026 is looking at contract rates near 4.8% to 5.2%, meaning a qualifying rate above 6.8% if they needed to refinance. But they do not need to requalify, they just renew. The bank approved them five years ago. The new payment is 60% higher. The test is silent.
What a Real Stress Test Looks Like
Test your own exposure by calculating three scenarios. First: what happens to discretionary income if your rate rises 200 basis points from today's level, not from the level you qualified at? Second: what happens if one income disappears for six months? Third: what happens if you need to sell in a flat market and your equity has not grown?
If any of those scenarios leaves you unable to contribute to an RRSP, cover an emergency car repair, or pay for your child's daycare without adding credit card debt, you have failed your own stress test. The bank does not care. The bank got its approval. You are the one left managing the gap between what you were qualified to borrow and what you can actually carry.
The regulatory test protects the system. Your test protects you. They are not the same thing.


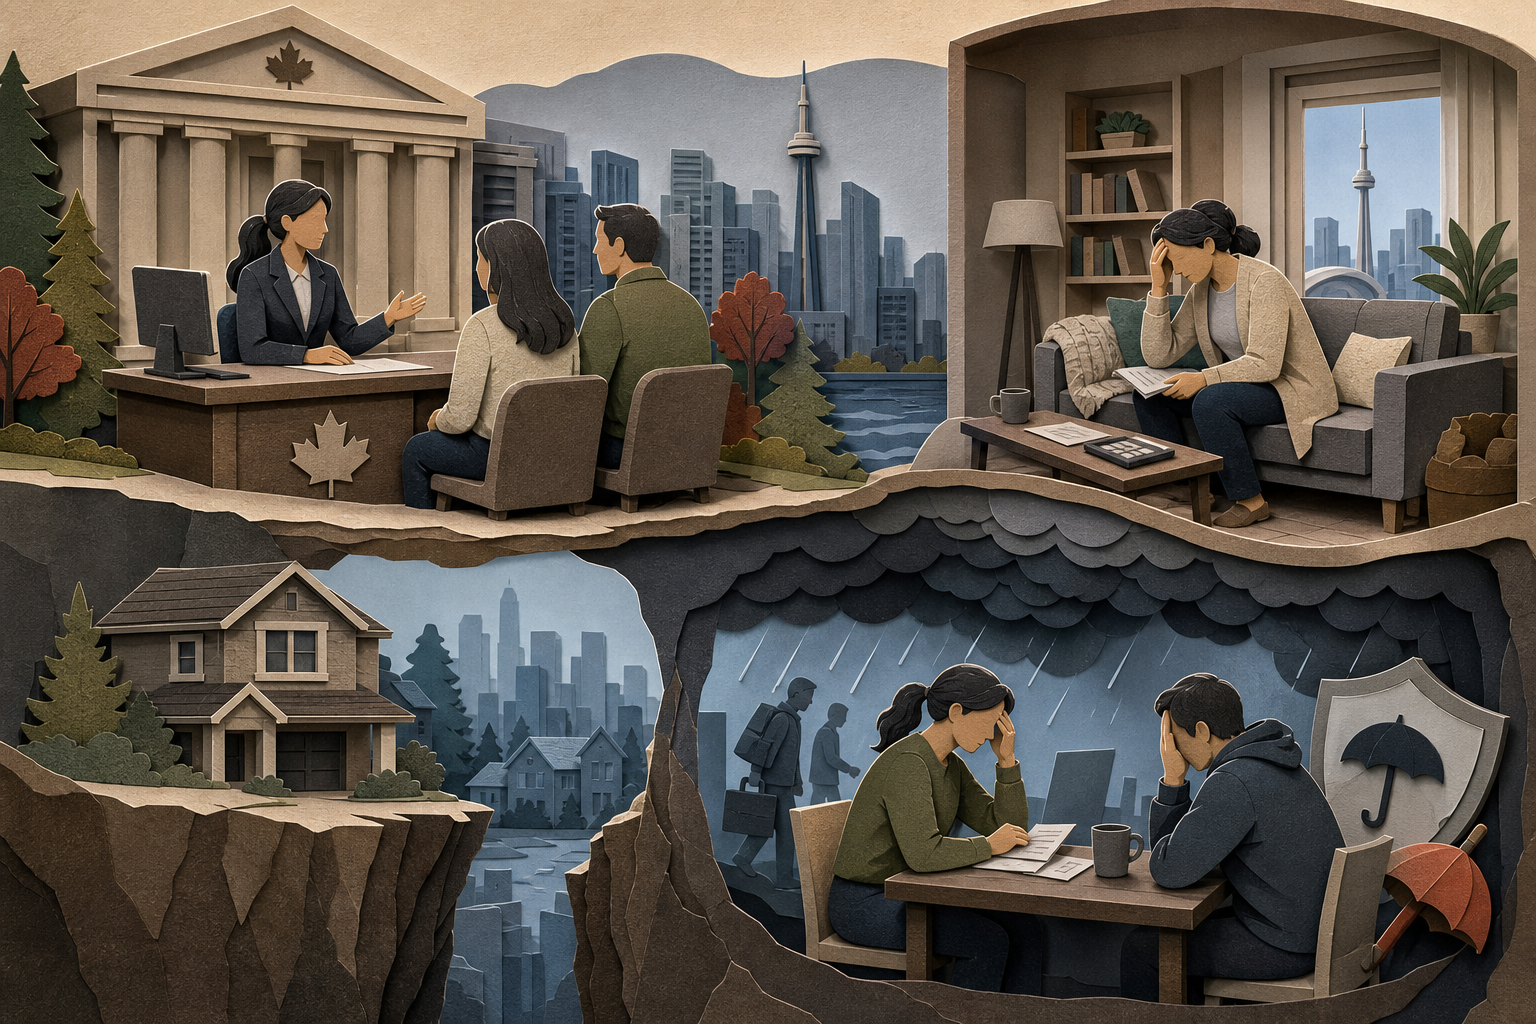

A borrower in Markham closed on a $680,000 mortgage in March 2021 at 1.49% variable. She qualified under the stress test at 5.25%. Two years later, her rate sat at 6.45%, higher than the rate she was tested against, and her monthly payment had climbed $1,340. She passed the bank's test. The bank got paid. She sold the house.
The Office of the Superintendent of Financial Institutions requires lenders to qualify borrowers at the higher of the contract rate plus 200 basis points or a floor rate of 5.25%. This is OSFI Guideline B-20, and it has been in place since 2018. The purpose is systemic: to prevent a wave of defaults that would threaten the stability of the financial system. It does that job. What it does not do is protect the individual borrower from payment shock at renewal or from lifestyle erosion during a rate cycle.
What the Test Actually Measures
The stress test calculates two ratios. Gross Debt Service accounts for shelter costs: mortgage payment, property tax, heating, and half of condo fees. Total Debt Service adds all other debt: car loans, credit cards, lines of credit. The maximums are typically 39% and 44% of gross household income. If you clear those thresholds at the stressed rate, you qualify.
Notice what is missing. Childcare, which for two kids in Toronto runs $2,800 a month. Groceries, up 22% since 2021 according to Statistics Canada. Private school. Car insurance, which in Ontario has climbed 15% in two years. The bank's formula treats discretionary income as infinite once debt service is covered, ignoring the groceries you buy, the childcare your kids need, and the car insurance you cannot skip.
The test also ignores timing. It measures affordability at application, when income is declared and debt is frozen in time. Three years later, you may have added a car lease, a second child, or a home equity line of credit to cover a kitchen reno. The original stress test did not anticipate those.
The Variable Rate Problem
Variable-rate holders with static payments face a structural trap the stress test does not address. As rates rise, more of each payment goes to interest. Eventually you hit the trigger point: your monthly payment only covers interest, and principal begins to grow. CIBC estimated in early 2024 that 32% of its variable-rate mortgage holders had reached trigger.
The stress test confirmed you could afford a higher rate. It did not confirm you could afford a mortgage balance that increases month over month while your equity shrinks.
The Renewal Wall
Roughly $340 billion in mortgages are renewing between 2025 and 2027, most of them originated when five-year fixed rates sat below 2.5%. A borrower who locked in at 1.79% in 2020 qualified at 4.79%. That same borrower renewing in 2026 is looking at contract rates near 4.8% to 5.2%, meaning a qualifying rate above 6.8% if they needed to refinance. But they do not need to requalify, they just renew. The bank approved them five years ago. The new payment is 60% higher. The test is silent.
What a Real Stress Test Looks Like
Test your own exposure by calculating three scenarios. First: what happens to discretionary income if your rate rises 200 basis points from today's level, not from the level you qualified at? Second: what happens if one income disappears for six months? Third: what happens if you need to sell in a flat market and your equity has not grown?
If any of those scenarios leaves you unable to contribute to an RRSP, cover an emergency car repair, or pay for your child's daycare without adding credit card debt, you have failed your own stress test. The bank does not care. The bank got its approval. You are the one left managing the gap between what you were qualified to borrow and what you can actually carry.
The regulatory test protects the system. Your test protects you. They are not the same thing.
Read Next
How Dual Citizens Can Claim RESP Tax Benefits Without Form 3520 Reporting
Bond Markets Are Pricing In Recovery, Not the 1970s Replay Already Underway
Why Fortress Tells Private Credit Lenders to Stop Chasing AI Data Centre Deals
Canada's Tax Code Punishes Work and Rewards Wealth Hoarding: Four Reforms That Would Actually Fix It