Why Walking Away From Your Mortgage Works in America but Destroys Canadians
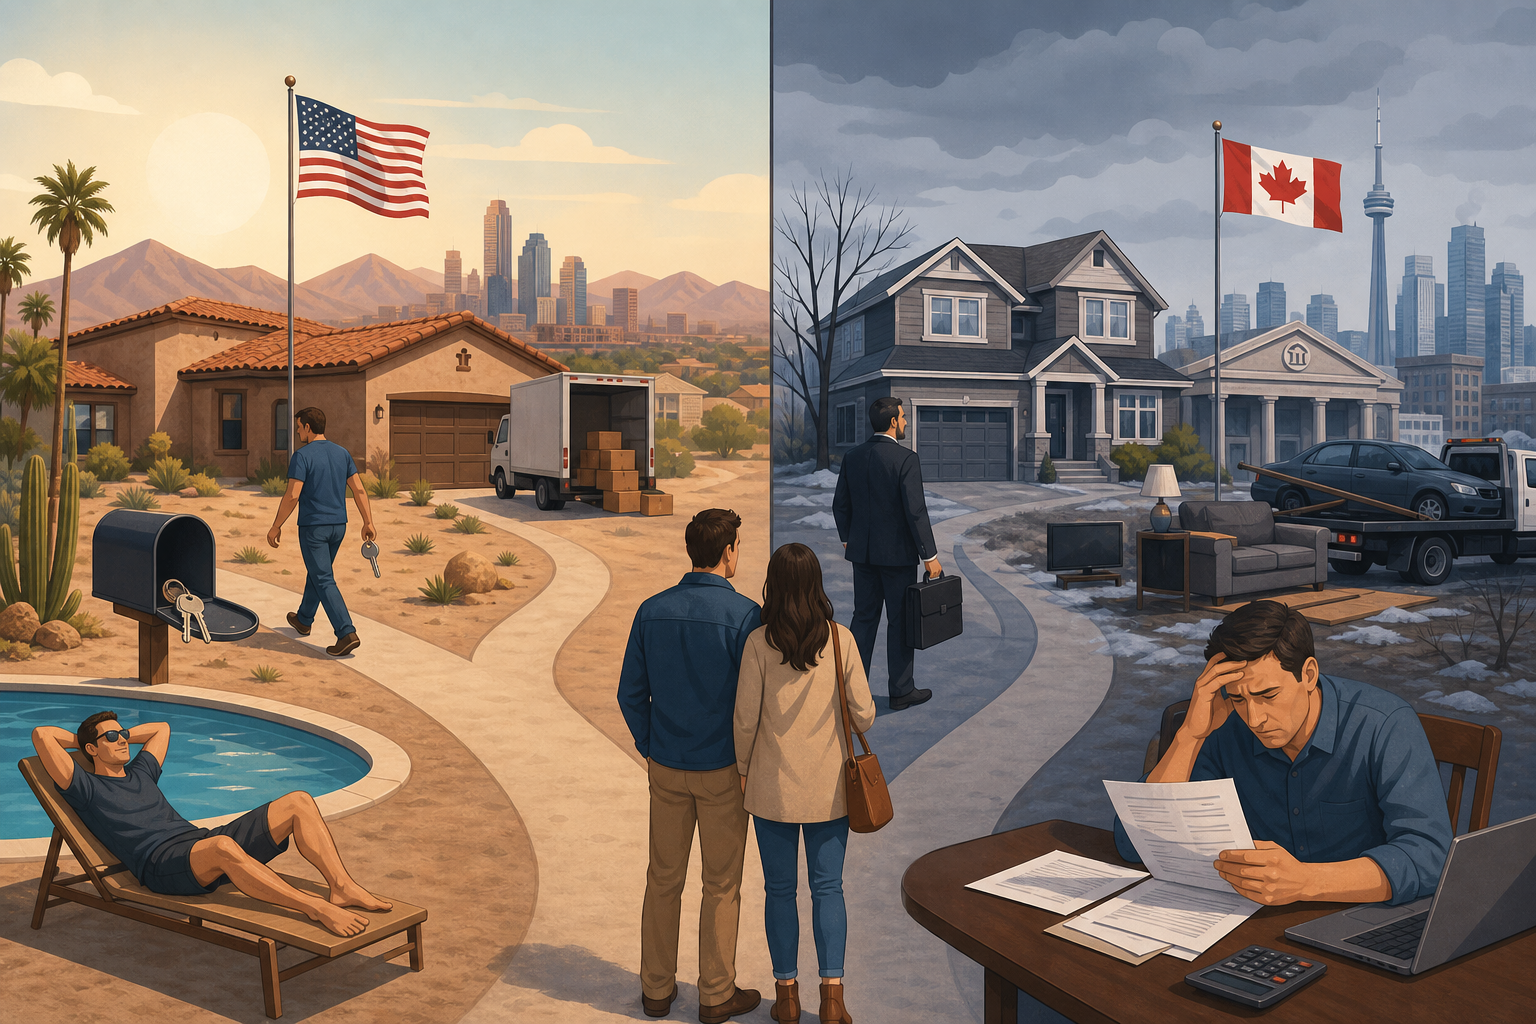
A homeowner in Phoenix who walked away from an underwater mortgage in 2009 left the keys on the counter, took a credit hit for seven years, and moved on. The lender ate the loss. A homeowner in Mississauga who tries the same thing today will find that the story doesn't end when the bank takes the house. It continues, sometimes for decades, because the legal architecture underneath Canadian mortgages is built differently.
The Recourse Rule Changes Everything
Most Canadian mortgages are recourse loans. That term means the lender's claim doesn't stop at the property. If the house sells for less than what you owe, the lender can pursue your other assets: wages, savings, investment accounts, vehicles. The shortfall becomes a debt you carry until it's paid or discharged through bankruptcy.
In much of the United States, mortgages are non-recourse by default or by state law. The lender's only remedy is the property itself. If the borrower hands over the keys and the sale doesn't cover the loan, the lender absorbs the gap. That structural difference is what made "jingle mail", the term for mailing your keys back to the bank, a rational strategy during the 2008 collapse in states like California and Arizona. The legal system capped the downside at your equity and your credit score.
Canada has two provinces with partial non-recourse protections: Alberta and Saskatchewan. But even there, the protection typically applies only to conventional mortgages with at least 20% down. Any mortgage insured by CMHC or Sagen, required for down payments under 20%, remains recourse across the country. The insurance doesn't protect the borrower. It protects the lender from loss, and the insurer retains the right to sue the borrower for the shortfall after paying the lender's claim.
What Actually Happens in a Canadian Default
Ontario, British Columbia, PEI, and New Brunswick use a process called Power of Sale. The lender can force the sale of your home without a court order, but they have a fiduciary duty to sell it at fair market value. If the sale brings in more than the outstanding debt, you get the surplus. If it brings in less, you owe the deficiency.
The deficiency becomes a judgment. In Ontario, the lender has two years from the date of default to sue for it. Once they have the judgment, they can garnish up to 20% of your gross wages. That garnishment can continue indefinitely until the debt is satisfied, and the judgment itself can be renewed every six years. A house you couldn't afford in your thirties can drain your paychecks in your forties and fifties.
Even if you negotiate a voluntary surrender, handing over the title doesn't automatically extinguish the debt. Unless the lender agrees in writing to accept the property as full settlement, they retain the right to pursue the shortfall. Many borrowers assume that giving up the house ends the obligation. It does not.
The Credit Damage Compounds the Financial One
A voluntary surrender or a completed Power of Sale stays on your credit file for six to seven years. During that time, you're essentially locked out of prime lending. No mortgage, no car loan at a reasonable rate, often no credit card with a meaningful limit. Landlords run credit checks. Employers in financial services sometimes do too.
The combination of the deficiency judgment and the credit damage creates a trap that doesn't exist in non-recourse jurisdictions. You can't borrow your way into a replacement property, and you're paying down a debt tied to an asset you no longer own. Bankruptcy or a consumer proposal become the most viable exits, which means the "walk away" that seemed like a clean break leads directly into insolvency proceedings anyway.
Why the System Works This Way
Recourse lending keeps the Canadian banking system stable. Borrowers can't offload risk onto lenders costlessly, so they default less often. Canada's mortgage delinquency rate has historically sat below 0.5%, a fraction of what the US saw during the financial crisis. The design works for the system. It just doesn't work for the borrower who thought walking away was an option.



A homeowner in Phoenix who walked away from an underwater mortgage in 2009 left the keys on the counter, took a credit hit for seven years, and moved on. The lender ate the loss. A homeowner in Mississauga who tries the same thing today will find that the story doesn't end when the bank takes the house. It continues, sometimes for decades, because the legal architecture underneath Canadian mortgages is built differently.
The Recourse Rule Changes Everything
Most Canadian mortgages are recourse loans. That term means the lender's claim doesn't stop at the property. If the house sells for less than what you owe, the lender can pursue your other assets: wages, savings, investment accounts, vehicles. The shortfall becomes a debt you carry until it's paid or discharged through bankruptcy.
In much of the United States, mortgages are non-recourse by default or by state law. The lender's only remedy is the property itself. If the borrower hands over the keys and the sale doesn't cover the loan, the lender absorbs the gap. That structural difference is what made "jingle mail", the term for mailing your keys back to the bank, a rational strategy during the 2008 collapse in states like California and Arizona. The legal system capped the downside at your equity and your credit score.
Canada has two provinces with partial non-recourse protections: Alberta and Saskatchewan. But even there, the protection typically applies only to conventional mortgages with at least 20% down. Any mortgage insured by CMHC or Sagen, required for down payments under 20%, remains recourse across the country. The insurance doesn't protect the borrower. It protects the lender from loss, and the insurer retains the right to sue the borrower for the shortfall after paying the lender's claim.
What Actually Happens in a Canadian Default
Ontario, British Columbia, PEI, and New Brunswick use a process called Power of Sale. The lender can force the sale of your home without a court order, but they have a fiduciary duty to sell it at fair market value. If the sale brings in more than the outstanding debt, you get the surplus. If it brings in less, you owe the deficiency.
The deficiency becomes a judgment. In Ontario, the lender has two years from the date of default to sue for it. Once they have the judgment, they can garnish up to 20% of your gross wages. That garnishment can continue indefinitely until the debt is satisfied, and the judgment itself can be renewed every six years. A house you couldn't afford in your thirties can drain your paychecks in your forties and fifties.
Even if you negotiate a voluntary surrender, handing over the title doesn't automatically extinguish the debt. Unless the lender agrees in writing to accept the property as full settlement, they retain the right to pursue the shortfall. Many borrowers assume that giving up the house ends the obligation. It does not.
The Credit Damage Compounds the Financial One
A voluntary surrender or a completed Power of Sale stays on your credit file for six to seven years. During that time, you're essentially locked out of prime lending. No mortgage, no car loan at a reasonable rate, often no credit card with a meaningful limit. Landlords run credit checks. Employers in financial services sometimes do too.
The combination of the deficiency judgment and the credit damage creates a trap that doesn't exist in non-recourse jurisdictions. You can't borrow your way into a replacement property, and you're paying down a debt tied to an asset you no longer own. Bankruptcy or a consumer proposal become the most viable exits, which means the "walk away" that seemed like a clean break leads directly into insolvency proceedings anyway.
Why the System Works This Way
Recourse lending keeps the Canadian banking system stable. Borrowers can't offload risk onto lenders costlessly, so they default less often. Canada's mortgage delinquency rate has historically sat below 0.5%, a fraction of what the US saw during the financial crisis. The design works for the system. It just doesn't work for the borrower who thought walking away was an option.
Read Next
How Dual Citizens Can Claim RESP Tax Benefits Without Form 3520 Reporting
Bond Markets Are Pricing In Recovery, Not the 1970s Replay Already Underway
Why Fortress Tells Private Credit Lenders to Stop Chasing AI Data Centre Deals
Canada's Tax Code Punishes Work and Rewards Wealth Hoarding: Four Reforms That Would Actually Fix It