Why Your Mortgage Broker's Lender Network Matters More Than the Rate They Quote
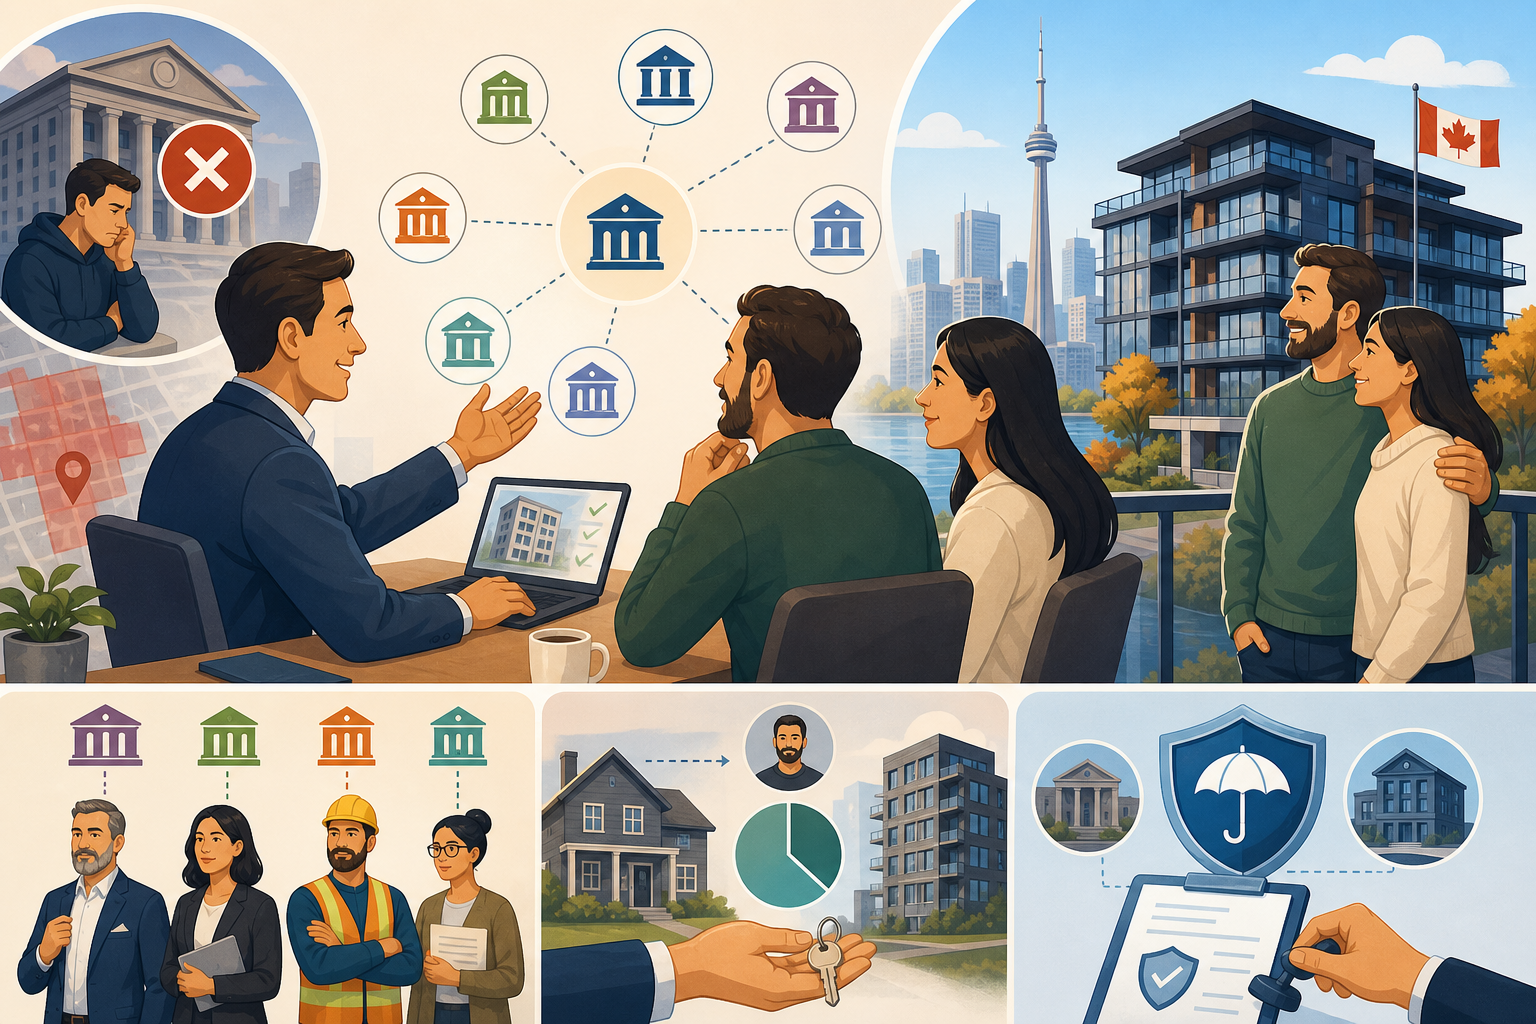
A client came to me last year with a 780 credit score and stable employment. The bank had declined him for a mortgage on a $620,000 condo. Not because of his finances, those were flawless. The property was over 600 square feet, the building was under 40 years old, the condo fees were reasonable. The bank simply didn't lend in that postal code. Their internal risk department had blacklisted a 12-block radius because of prior delinquency patterns in the neighborhood.
We moved him to a monoline lender whose underwriting team evaluated the specific building rather than the postal code. He closed three weeks later at 5.19%, which was 0.05% higher than the bank's posted rate. The difference cost him $31 per month. The alternative was not getting a mortgage at all.
That is what a lender network actually does. It isn't about shopping for the best price on an identical product. It's about accessing institutions that will say yes to your specific file when others say no.
The Underwriting Personality Problem
Every lender has criteria, and those criteria differ in ways that don't show up in rate sheets. Some lenders count 100% of commission income if you've been in the same industry for two years. Others average it over three years or discount it by 25%. Some accept two months of bank statements for self-employed borrowers. Others require two years of tax returns and will scrutinize every deduction.
Credit unions in Ontario often allow debt service ratios up to 44% on the total debt service (TDS) side, while the Big Six banks keep it closer to 42%. That 2% difference is the gap between qualifying for the home you want and settling for something smaller.
A broker with 15 lenders can route a file to the institution whose underwriting philosophy fits the borrower's income structure. A broker with three lenders just tells you to fix your tax returns and try again next year.
Product Features You Don't See Until You Need Them
Prepayment privileges at major banks typically allow 10% to 20% of the original principal to be repaid annually without penalty. Some monolines allow 25%. If you sell a rental property or receive an inheritance and want to knock down your mortgage balance, that extra 5% or 10% can mean paying off tens of thousands without triggering penalties.
Portability rules vary just as much. Most major banks allow you to port your mortgage if you're moving within the same province and the new property value is within a reasonable range of the old one. Some lenders won't port across provincial lines. Others won't port if you're upgrading by more than 30% in value. If you're moving from a $400,000 townhouse in Hamilton to a $700,000 detached in Oakville, some lenders will treat that as breaking your existing mortgage and applying for a new one, meaning you'll pay the interest rate differential penalty.
Breaking a five-year fixed mortgage with a major bank right now can cost three to four times what it costs with a monoline lender. The banks calculate the penalty using their posted rates, which sit 1.5% to 2% higher than the discounted rate you actually got. Monolines use your contract rate. On a $500,000 mortgage with three years remaining, that difference can be $18,000 versus $6,000.
The B-Lender Layer
When traditional lenders say no, because of a recent credit bruise, self-employed income they can't verify through tax returns, or a property type they don't touch, alternative lenders exist specifically to fill that space. They charge 1% to 2.5% more in interest and often add a 1% lender fee, but they use stated income, equity-based criteria, or relaxed credit requirements.
A broker with access to Home Trust, Equitable, or regional credit unions can get a deal done where a bank-only approach leaves you with nothing. The rate difference matters less than the fact that you close.
The lowest rate you see advertised is often attached to a restricted mortgage: high exit penalties, no refinancing without selling the home, minimal prepayment options. That rate is bait. A broker who only pushes the lowest number is selling you the wrong product.
The network matters because your life doesn't fit one lender's box. It fits someone's, and the broker's job is knowing whose.



A client came to me last year with a 780 credit score and stable employment. The bank had declined him for a mortgage on a $620,000 condo. Not because of his finances, those were flawless. The property was over 600 square feet, the building was under 40 years old, the condo fees were reasonable. The bank simply didn't lend in that postal code. Their internal risk department had blacklisted a 12-block radius because of prior delinquency patterns in the neighborhood.
We moved him to a monoline lender whose underwriting team evaluated the specific building rather than the postal code. He closed three weeks later at 5.19%, which was 0.05% higher than the bank's posted rate. The difference cost him $31 per month. The alternative was not getting a mortgage at all.
That is what a lender network actually does. It isn't about shopping for the best price on an identical product. It's about accessing institutions that will say yes to your specific file when others say no.
The Underwriting Personality Problem
Every lender has criteria, and those criteria differ in ways that don't show up in rate sheets. Some lenders count 100% of commission income if you've been in the same industry for two years. Others average it over three years or discount it by 25%. Some accept two months of bank statements for self-employed borrowers. Others require two years of tax returns and will scrutinize every deduction.
Credit unions in Ontario often allow debt service ratios up to 44% on the total debt service (TDS) side, while the Big Six banks keep it closer to 42%. That 2% difference is the gap between qualifying for the home you want and settling for something smaller.
A broker with 15 lenders can route a file to the institution whose underwriting philosophy fits the borrower's income structure. A broker with three lenders just tells you to fix your tax returns and try again next year.
Product Features You Don't See Until You Need Them
Prepayment privileges at major banks typically allow 10% to 20% of the original principal to be repaid annually without penalty. Some monolines allow 25%. If you sell a rental property or receive an inheritance and want to knock down your mortgage balance, that extra 5% or 10% can mean paying off tens of thousands without triggering penalties.
Portability rules vary just as much. Most major banks allow you to port your mortgage if you're moving within the same province and the new property value is within a reasonable range of the old one. Some lenders won't port across provincial lines. Others won't port if you're upgrading by more than 30% in value. If you're moving from a $400,000 townhouse in Hamilton to a $700,000 detached in Oakville, some lenders will treat that as breaking your existing mortgage and applying for a new one, meaning you'll pay the interest rate differential penalty.
Breaking a five-year fixed mortgage with a major bank right now can cost three to four times what it costs with a monoline lender. The banks calculate the penalty using their posted rates, which sit 1.5% to 2% higher than the discounted rate you actually got. Monolines use your contract rate. On a $500,000 mortgage with three years remaining, that difference can be $18,000 versus $6,000.
The B-Lender Layer
When traditional lenders say no, because of a recent credit bruise, self-employed income they can't verify through tax returns, or a property type they don't touch, alternative lenders exist specifically to fill that space. They charge 1% to 2.5% more in interest and often add a 1% lender fee, but they use stated income, equity-based criteria, or relaxed credit requirements.
A broker with access to Home Trust, Equitable, or regional credit unions can get a deal done where a bank-only approach leaves you with nothing. The rate difference matters less than the fact that you close.
The lowest rate you see advertised is often attached to a restricted mortgage: high exit penalties, no refinancing without selling the home, minimal prepayment options. That rate is bait. A broker who only pushes the lowest number is selling you the wrong product.
The network matters because your life doesn't fit one lender's box. It fits someone's, and the broker's job is knowing whose.
Read Next
How Dual Citizens Can Claim RESP Tax Benefits Without Form 3520 Reporting
Bond Markets Are Pricing In Recovery, Not the 1970s Replay Already Underway
Why Fortress Tells Private Credit Lenders to Stop Chasing AI Data Centre Deals
Canada's Tax Code Punishes Work and Rewards Wealth Hoarding: Four Reforms That Would Actually Fix It